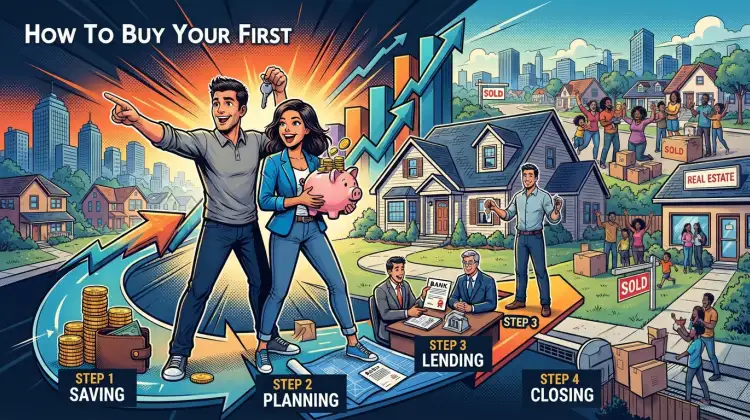
Buying your first home is one of the largest financial commitments you will ever make, and the process rewards preparation. In the US, the median sales price of an existing single-family home has hovered in the $400,000 range in recent years, according to the National Association of Realtors, so even a modest down payment represents serious money. This guide walks you through the sequence that experienced buyers and lenders follow, from checking your credit to picking up the keys.
1. Assess Your Finances Before You Shop
Start with the numbers, not the listings. Lenders evaluate three things: your credit score, your debt-to-income ratio (DTI), and your available cash. Most conventional loans look for a credit score of at least 620, while FHA loans backed by the Federal Housing Administration allow scores as low as 580 with a 3.5% down payment.
Your DTI compares total monthly debt payments to gross monthly income. Many lenders prefer a DTI at or below 36%, though some conventional programs allow up to 43% or higher with compensating factors. Use a mortgage calculator to estimate a payment that includes principal, interest, property taxes, homeowners insurance, and any HOA dues.
- Down payment: 20% avoids private mortgage insurance (PMI), but many first-time buyers put down far less.
- Closing costs: Budget 2% to 5% of the purchase price for lender fees, title insurance, and prepaid taxes.
- Reserves: Keep an emergency fund separate from your down payment.
2. Get Pre-Approved, Not Just Pre-Qualified
Pre-qualification is a quick estimate based on self-reported information. Pre-approval is stronger: the lender verifies your income, assets, and credit and issues a conditional commitment for a specific loan amount. In competitive markets, sellers often expect a pre-approval letter with an offer.
Compare at least three lenders, including a credit union or community bank. Rates and fees vary, and a difference of half a percentage point on a $350,000 loan can cost tens of thousands of dollars over 30 years. Ask each lender for a Loan Estimate, a standardized three-page form that makes side-by-side comparison straightforward.
Loan programs worth knowing
- Conventional loans: Backed by Fannie Mae or Freddie Mac; down payments as low as 3% for qualified first-time buyers.
- FHA loans: 3.5% down with a 580+ score; mortgage insurance premiums apply.
- VA loans: For eligible veterans, active-duty service members, and some surviving spouses; often 0% down.
- USDA loans: For eligible rural areas, also 0% down.
3. Build Your Team and Shop Strategically
A buyer's agent who works in your target neighborhoods can flag pricing trends, inspection issues, and negotiation levers you might miss. In most US transactions, the seller pays the buyer's agent commission, though commission structures have been evolving since the 2024 National Association of Realtors settlement. Confirm representation terms in writing before touring homes.
When you find a property, move quickly but carefully. Your agent will pull comparable sales to support an offer price. In a balanced market, asking for seller concessions toward closing costs is reasonable; in a hot market, you may need to waive minor contingencies — but never waive the inspection without understanding the risk.
4. From Offer to Closing Day
Once your offer is accepted, the clock starts. A typical timeline runs 30 to 45 days and includes:
- Home inspection: A licensed inspector examines the structure, roof, HVAC, plumbing, and electrical systems. You can request repairs or a price credit based on findings.
- Appraisal: Your lender orders an independent valuation. If it comes in below the purchase price, you may need to renegotiate or bring extra cash.
- Underwriting: The lender verifies your documents and issues a final approval. Avoid opening new credit cards or changing jobs during this window.
- Final walk-through: Confirm agreed repairs are complete and the home is in the expected condition.
- Closing: You sign the Closing Disclosure, pay remaining funds via wire or cashier's check, and receive the keys.
Review the Closing Disclosure at least three business days before closing. Federal rules require lenders to deliver it in that window so you can compare it against your original Loan Estimate and question any unexpected fees.
5. Plan for Life After Closing
Your first mortgage payment is typically due the first of the month after a full month of ownership. Set up autopay and confirm whether your lender escrows taxes and insurance or whether you pay them directly. New homeowners should also budget for maintenance — a common rule of thumb is 1% of the home's value annually. Keep receipts for improvements; they can reduce capital gains taxes when you eventually sell, thanks to the $250,000 primary-residence exclusion ($500,000 for married couples filing jointly).
The Short Version
Buying your first home comes down to preparation and sequence: strengthen your credit and DTI, save beyond the down payment, get pre-approved with multiple lenders, hire a buyer's agent who knows your market, and protect yourself with inspections and contingencies. Understand every fee on the Loan Estimate and Closing Disclosure, and keep reserves for maintenance after you move in. Do that, and the process becomes far less intimidating — and far more likely to end with keys in hand.