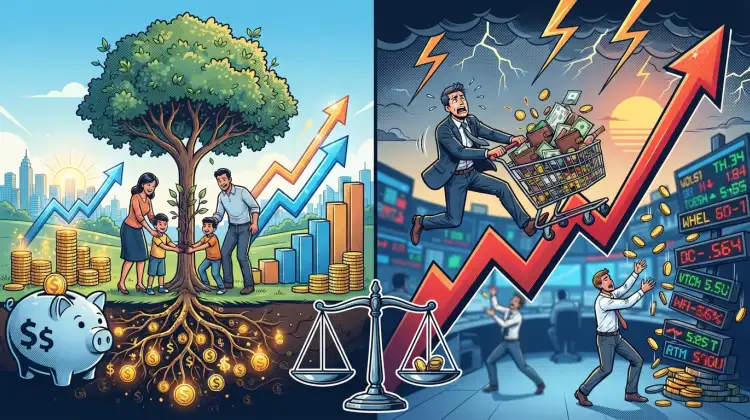
One of the first decisions every investor faces is how long to hold an investment. The choice between long term investing vs short term trading shapes your tax bill, your risk exposure, and ultimately how much of your money you keep. Neither approach is inherently wrong, but they serve very different goals and demand very different skills. Understanding the mechanics behind each can help you match a strategy to your timeline, temperament, and account type.
What Counts as Long Term vs Short Term
The dividing line is largely defined by the IRS. For tax purposes, the long-term capital gains rate applies to assets held for more than one year, while positions held one year or less are taxed at ordinary income rates. That single rule creates a meaningful gap in after-tax returns.
For 2024, long-term capital gains rates are 0%, 15%, or 20%, depending on taxable income and filing status. Short-term gains are taxed at your marginal rate, which can reach 37% at the top bracket. A $10,000 gain held 13 months might be taxed at 15% ($1,500), while the same gain realized in 11 months could be taxed at 24% or higher. Over a career of investing, that spread compounds against frequent traders.
Beyond taxes, the two approaches differ in philosophy. Long-term investors buy businesses, funds, or bonds and hold through market cycles. Short-term traders aim to profit from price swings over days, weeks, or months, often using technical signals rather than fundamentals.
Risk, Volatility, and Time Horizon
Time is the most powerful risk-management tool available to individual investors. Historically, the S&P 500 has produced positive returns in roughly three out of every four calendar years, but the odds of a positive outcome rise as the holding period lengthens. According to research from Vanguard, rolling 10-year periods in the U.S. stock market have rarely produced losses, while single-year results swing widely.
Short-term strategies compress that timeline and magnify volatility. A trader can be right about a company's direction and still lose money to a gap down, a bad earnings reaction, or a broad market selloff. Long-term investors absorb those shocks because they are not forced to sell at the bottom.
- Long term: Lower turnover, lower taxes, dividends and interest compound, less screen time.
- Short term: Higher turnover, higher taxes, greater emotional demands, potential for quick gains or losses.
Costs, Taxes, and Compounding
Costs quietly erode short-term returns. Every trade may incur a commission, a bid-ask spread, and slippage. Frequent trading inside a taxable brokerage account also triggers capital gains events that reduce the capital available to compound.
Long-term investors benefit from tax deferral. Unrealized gains are not taxed until you sell, so the full balance keeps working. In tax-advantaged accounts like a 401(k) or IRA, that advantage is even stronger because contributions and growth can grow without annual tax drag.
Compounding rewards patience. A $10,000 investment earning 7% annually grows to about $19,700 in 10 years and roughly $76,100 in 30 years, assuming no additional contributions. Interrupting that compounding with frequent sales can reset the clock.
When Short-Term Strategies Make Sense
Short-term investing is not automatically reckless. It can be appropriate when you have a specific, near-term goal, such as saving for a home down payment in two years. In that case, a money market fund, Treasury bill, or short-term certificate of deposit may be a better fit than stocks, because the priority is protecting principal rather than maximizing growth.
Some experienced investors also allocate a small "satellite" portion of a portfolio to tactical trades while keeping the core in diversified, long-term holdings. The key is sizing that sleeve so a losing streak does not derail your broader plan. A common guideline is to risk no more than 5% to 10% of investable assets on active short-term positions.
How to Choose an Approach
Start with the goal and the deadline, not the strategy. Ask yourself:
- When do I need this money?
- Can I tolerate a 20% to 30% drawdown without selling?
- How much time can I realistically devote to research and monitoring?
- What is my tax bracket, and which accounts hold these assets?
If the money is for retirement decades away, a low-cost, diversified portfolio of index funds and bonds held for the long term is hard to beat. If the money is needed within a few years, short-duration, lower-volatility instruments are usually the wiser choice. If you enjoy trading and can afford the risk, keep it separate from your core plan and track your results honestly against a simple benchmark like the S&P 500.
What to Remember
The debate between long term investing vs short term is less about which is superior and more about which matches your goal, timeline, and temperament. Long-term investing offers tax advantages, lower costs, and the full benefit of compounding, making it the default for retirement and wealth building. Short-term strategies can serve near-term needs or a small tactical allocation, but they demand more time, higher taxes, and stronger emotional discipline. Most investors build wealth by keeping the core of their portfolio long term and using short-term tools only where the goal truly calls for them.







