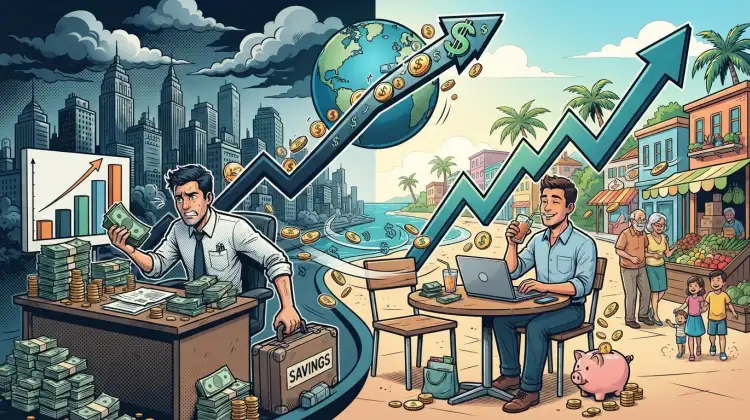
Geoarbitrage is the practice of deliberately separating where you earn your income from where you spend it, so that the gap between the two cost structures works in your favor. For someone pursuing financial independence, that gap is not a gimmick — it is a lever. If your income is generated in a high-wage market like the United States and a meaningful share of your expenses are paid in a lower-cost location, every dollar you save buys more progress toward your FI number.
The concept gained mainstream attention through Tim Ferriss's The 4-Hour Workweek and later through the FIRE community, but the underlying economics are older than either. The term is a portmanteau of geography and arbitrage, the practice of profiting from price differences between markets. Applied to personal finance, it means treating your cost of living as a variable you control rather than a fixed constraint.
How Geoarbitrage Actually Works
At its core, geoarbitrage is a ratio problem. Your savings rate — the percentage of income you keep — is the single strongest predictor of how quickly you reach financial independence. A person earning $80,000 and spending $70,000 saves 12.5%. The same $80,000 earned while spending $40,000 saves 50%. That difference can compress a 40-year working career into roughly 15 years, because the math of compounding rewards a high savings rate far more than it rewards investment returns alone.
There are three broad models:
- Remote employment: You keep a U.S. salary and work remotely from a lower-cost area, whether that is a smaller American city or another country. This is the highest-leverage version because your income stays anchored to a strong labor market.
- Location-independent business: You run a service, consulting practice, or digital product business priced in dollars while your operating costs sit in a cheaper market.
- Retirement relocation: You accumulate assets in an expensive city, then withdraw and spend them somewhere with lower housing, healthcare, and tax costs.
Each model shares the same mechanic: your earning power is priced in one market, your consumption in another.
The Real Savings: Housing, Healthcare, and Taxes
Housing is almost always the largest line item, and it is where geoarbitrage delivers the most immediate impact. According to the U.S. Bureau of Labor Statistics Consumer Expenditure Survey, housing consumes roughly a third of the average American household budget. Moving from a high-cost metro to a mid-cost one can cut that figure in half without touching your income.
Healthcare is the second major lever, particularly for early retirees who are not yet eligible for Medicare at 65. Under the Affordable Care Act, premiums are subsidized based on household income relative to the federal poverty level, and those subsidies are calculated using the cost of the benchmark plan in your rating area. A lower-cost region can mean both cheaper premiums and a lower income threshold to qualify for assistance. This is a genuinely American consideration that many geoarbitrage guides overlook.
Taxes are the third. The U.S. taxes citizens on worldwide income regardless of residence, so moving abroad does not eliminate federal tax. However, the Foreign Earned Income Exclusion allows qualifying expats to exclude a substantial amount of earned income from federal tax, and state income tax can often be eliminated entirely by establishing residency in a state with no income tax. Sales tax, property tax, and vehicle costs also vary widely by state.
What Geoarbitrage Does Not Fix
It is important to be honest about the limits. Geoarbitrage does not repair a spending problem, and it does not create income. If your savings rate is low because you spend everything you earn, moving somewhere cheaper often just resets your baseline — you adjust to the new normal and save the same percentage.
It also introduces real frictions:
- Income risk: Remote roles can be reclassified or localized, and employers may adjust pay to reflect your new location.
- Visa and legal complexity: Working remotely from another country may require a specific visa category, and compliance rules are not uniform.
- Social and family costs: Distance from aging parents, children's schooling, and support networks has a value that does not appear on a spreadsheet.
- Currency risk: If your income is in dollars and your expenses are in another currency, exchange-rate swings can erase your advantage.
How to Evaluate a Geoarbitrage Move
Start with your own numbers rather than rankings of "cheapest places to live." Build a spreadsheet with four columns: current monthly expenses, estimated expenses in the new location, expected income after any adjustment, and one-time transition costs. Then calculate your projected savings rate in both scenarios.
Next, stress-test the plan. What happens if your rent rises 20%? If your employer cuts pay by 15%? If the dollar weakens against the local currency? A move that only works under ideal conditions is not a strategy — it is a bet.
Finally, run a trial. Spend one to three months in the target location before committing to a lease, a job change, or a residency move. The cost of a trial is trivial compared with the cost of reversing a permanent relocation.
Geoarbitrage and the FI Timeline
For most people, geoarbitrage is best understood as an accelerant rather than a destination. It works alongside the other pillars of financial independence: a high savings rate, low fixed costs, diversified index-fund investing through tax-advantaged accounts like a 401(k) and Roth IRA, and income growth through skills or side work.
Used carefully, it can shave years off your timeline. Used carelessly, it can become an excuse to postpone the harder work of spending discipline and income growth.
The Short Version
Geoarbitrage means earning in one market and spending in a cheaper one, and its power comes from raising your savings rate rather than from any single expense category. The biggest real savings are in housing, healthcare, and taxes — all of which vary enormously across U.S. states and abroad. But it cannot fix overspending, it carries income, legal, and currency risks, and it should be tested with a trial stay before you commit. Treat it as one tool in a broader financial independence plan, not a shortcut around one.







