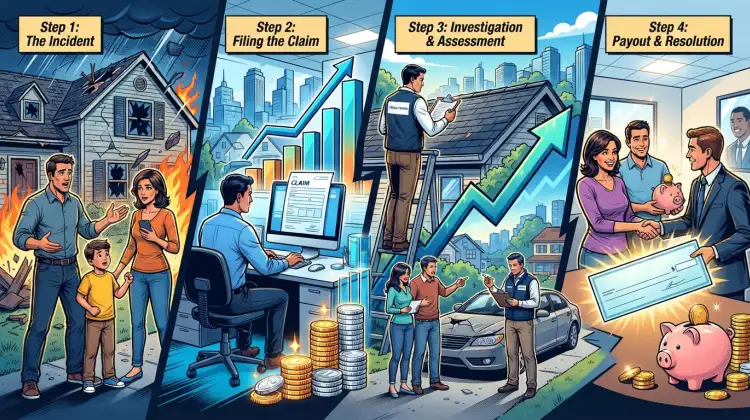
Filing an insurance claim is the moment your policy stops being a piece of paper and becomes a financial tool. Whether you are recovering from a burst pipe, a fender bender, or a hospital stay, the insurance claims process follows a predictable arc: notice, investigation, evaluation, and payment or denial. Understanding each stage helps you document your loss correctly, avoid delays, and push back when a settlement offer falls short of what your policy promises.
Step 1: Report the Loss Promptly
Your duties as a policyholder begin the moment a covered loss occurs. Most policies require "prompt" notice, and some set hard deadlines. Auto policies commonly require notice within 20 to 30 days; homeowners policies often allow up to 60 days but reward speed because evidence degrades. Health plans typically require claims within 90 to 365 days of service, depending on the plan and whether the provider is in network.
Call your insurer's claims line or file through its app or website. You will receive a claim number, the name of the adjuster assigned to your file, and a list of documents to submit. Write down every conversation: date, time, representative name, and what was promised. If you cannot reach your insurer, send written notice by certified mail so you have proof of timely filing.
Step 2: Document Everything Before Cleanup
Adjusters decide claims based on evidence, and evidence disappears fast. Before you throw away damaged property or authorize repairs, photograph and video the damage from multiple angles, keep receipts for emergency repairs such as roof tarping or water extraction, and create an inventory of damaged items with purchase dates and prices where you can find them.
For auto claims, obtain a police report number and exchange insurance information with the other driver. For health claims, keep your explanation of benefits (EOB), itemized bills, and any denial notices. For homeowners claims, a written room-by-room inventory with photos is the single most persuasive document you can hand an adjuster.
Step 3: The Investigation and Adjuster Visit
The insurer assigns either a staff adjuster or an independent adjuster, and for large losses it may send a third-party vendor. The adjuster inspects the damage, reviews your documentation, and applies your policy's coverage terms, limits, and deductibles. You are entitled to a copy of the adjuster's report in most states.
Attend the inspection yourself. Point out every item of damage, ask what the adjuster is measuring, and request the scope of work in writing. If the adjuster's estimate misses items you can see, say so on the spot and follow up by email so your objection is in the file.
Step 4: Evaluation, Settlement, and Payment
After the investigation, the insurer issues a coverage decision. If the claim is approved, you receive a settlement or payment based on replacement cost or actual cash value, minus your deductible and any depreciation. Replacement cost coverage pays to rebuild or replace at today's prices; actual cash value pays today's price minus depreciation, which is usually thousands of dollars less on older roofs, vehicles, and electronics.
Review the payment letter line by line. Confirm that your deductible was applied once, that your policy limits were not exceeded incorrectly, and that recoverable depreciation was released after repairs were completed. If the offer is low, you can negotiate with the adjuster, request a re-inspection, or invoke your policy's appraisal clause, which lets each side hire an independent appraiser and a neutral umpire to resolve valuation disputes.
Step 5: What to Do If Your Claim Is Denied
A denial is not always final. Insurers must state the specific policy language they relied on. Common grounds include excluded perils, late notice, lack of proof of loss, or a dispute over whether damage was pre-existing. Your options:
- Internal appeal: Request a formal review in writing, citing the policy language and your evidence. Health plans must follow federal and state external review rules.
- Appraisal or mediation: Many homeowners policies include an appraisal clause for valuation disputes.
- State insurance department complaint: Every state has a department of insurance that accepts consumer complaints and publishes complaint ratios.
- Legal action: Consult an attorney, especially if the insurer acted in bad faith. Some states allow extra-contractual damages.
Keep a paper trail throughout. Regulators, arbitrators, and courts all weigh contemporaneous documentation heavily.
Timelines, State Rules, and Your Rights
States regulate claim handling through unfair claims settlement practices acts. Many require acknowledgment of a claim within 10 to 15 days, a decision within 30 to 45 days after proof of loss, and written notice of any extension. Health claims under the Affordable Care Act must be decided within 30 days for pre-service requests and 60 days for post-service appeals. Missed deadlines can strengthen your position, so log every date.
Key Takeaways
The insurance claims process rewards preparation: report losses promptly, document damage before cleanup, attend the adjuster's inspection, and read every settlement letter before cashing the check. If a claim is denied or undervalued, use internal appeals, appraisal clauses, and your state insurance department. Your policy is a contract, and knowing its claim duties and deadlines is the fastest route to a fair payout.







