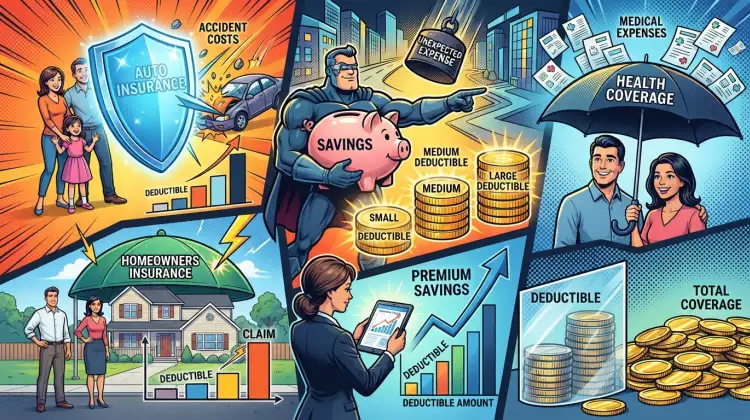
A deductible is the amount you agree to pay out of pocket before your insurance company pays a claim. It is one of the most important numbers in any policy, because it directly controls both what you pay each month and what you pay when something goes wrong. Understanding how deductibles work — and how insurers set them — helps you avoid surprises at claim time and choose coverage that actually fits your finances.
What Is an Insurance Deductible?
Your deductible is a fixed dollar amount you are responsible for on a covered loss. If you have a $1,000 deductible on your homeowners policy and a covered storm causes $5,000 in damage, you pay $1,000 and the insurer pays the remaining $4,000, minus any other applicable limits or exclusions. If the loss is $800 — less than your deductible — you pay the full amount yourself and the insurer pays nothing.
Deductibles appear across nearly every type of coverage:
- Auto insurance: A collision or comprehensive deductible, commonly $250 to $1,000.
- Homeowners and renters: A flat deductible, plus separate deductibles for perils like wind or hail in some states.
- Health insurance: An annual deductible you meet before most coverage kicks in, separate from copays and coinsurance.
- Life and disability insurance: Usually no deductible; the policy pays from the first dollar.
How Deductibles Affect Your Premium
Deductibles and premiums move in opposite directions. A higher deductible means you absorb more of each loss, so the insurer charges less. A lower deductible means the insurer takes on more risk, so you pay more every month.
The trade-off is not always proportional. Moving from a $500 to a $1,000 auto deductible might save 10% to 15% on your collision premium, while moving from $1,000 to $2,000 may save far less. The practical rule is to choose the highest deductible you could comfortably pay tomorrow, in cash, without borrowing — because that is exactly the scenario a claim creates.
A quick example
Suppose two drivers have identical cars and records. Driver A picks a $500 deductible and pays $1,200 a year. Driver B picks a $1,000 deductible and pays $1,020 a year. Driver B saves $180 annually but risks an extra $500 at claim time. After about three claim-free years, Driver B is ahead — unless a single at-fault accident wipes out the savings.
How Health Insurance Deductibles Differ
Health insurance works differently from property and casualty coverage. Your deductible is an annual threshold, not a per-claim charge. You pay the full negotiated cost of covered care until you reach it, then you typically pay coinsurance — a percentage of each bill — until you hit your out-of-pocket maximum, after which the plan pays 100% of covered in-network care.
Two features matter most:
- Embedded vs. aggregate family deductibles. With an embedded deductible, one family member can meet their individual limit and start receiving benefits even if the family total is not reached. With an aggregate deductible, the whole family must hit the combined amount first.
- Preventive care. Under the Affordable Care Act, most ACA-compliant plans cover in-network preventive services without requiring you to meet the deductible.
If you expect regular care, run the math on total annual cost — premiums plus expected out-of-pocket spending — rather than comparing deductibles alone.
Special Deductibles You Should Know About
Not every deductible is a single flat number. Watch for these variations:
- Percentage deductibles. Common for hurricane, wind, and hail coverage in coastal states such as Florida and Texas. A 2% deductible on a $400,000 home means $8,000 out of pocket.
- Split deductibles. Auto policies often separate collision from comprehensive, so a cracked windshield and a fender bender carry different amounts.
- Per-occurrence vs. annual. Property policies usually apply the deductible once per event; health plans apply it once per plan year.
- Disappearing deductibles. Some auto insurers reduce your deductible by a set amount each claim-free year.
How to Choose the Right Deductible
Start with your emergency fund. A deductible you cannot pay is not real protection — it is a future credit card balance. Then work through these steps:
- Set your comfort ceiling. Pick the largest amount you could cover within a few days without touching retirement savings.
- Price the trade-off. Ask your agent or insurer for quotes at two or three deductible levels and compare the annual premium difference.
- Check lender requirements. Mortgage servicers and auto lenders may cap how high your deductible can go.
- Review annually. As your savings grow, raising a deductible can free up premium dollars for better uses.
- Do not over-insure small losses. Filing a $900 claim against a $500 deductible may raise your premium more than it pays out.
One more caution: filing frequent small claims can lead insurers to non-renew a homeowners policy or surcharge an auto policy. Deductibles exist partly to keep small losses off the insurer's books, which is why they help hold premiums down for everyone.
Frequently Asked Questions
Does a deductible apply to every claim?
No. Liability coverage — such as the bodily injury and property damage portions of an auto policy — generally has no deductible. Deductibles apply to coverage for your own property or injuries, like collision, comprehensive, and homeowners claims.
Can I change my deductible mid-policy?
Usually yes, but the change typically takes effect at renewal or requires a policy endorsement. Lowering a deductible mid-term may trigger an additional premium charge; raising it may produce a partial refund.
Is a higher deductible always better?
Only if you can absorb the out-of-pocket cost. A high deductible lowers premiums but shifts real risk onto you. The right choice balances premium savings against the cash you can access on short notice.
The Short Version
A deductible is the share of a covered loss you pay before insurance responds. Higher deductibles lower premiums but raise your exposure; lower deductibles do the reverse. Health plans treat the deductible as an annual threshold tied to coinsurance and an out-of-pocket maximum, while property and auto policies usually apply it per claim. Percentage deductibles for wind and hail can be far larger than they first appear. Choose the highest deductible you can pay in cash without strain, compare premium quotes at several levels, and revisit the decision each year as your savings and needs change.







